
Read this article in 中文 Français Deutsch Italiano Português Español
Oil and gas companies remain key adopters of CCUS
August 25, 2026
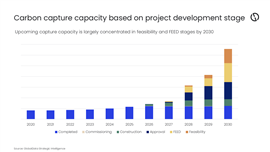
Carbon capture, utilization, and storage (CCUS) has become an important decarbonization pathway for oil and gas, power, cement, steel and other hard-to-abate industries, according to GlobalData’s Strategic Intelligence report, “Carbon Capture and Storage”.
As of June 2026, more than 70% of operational and upcoming carbon capture facilities, by facility count, were associated with energy assets, with oil and gas companies remaining key participants, even though many have scaled back broader low-carbon investments, the report indicated.
The report went on to reveal that several oil and gas companies continue to prioritize CCUS where it supports core assets, including LNG, refining, hydrogen production and upstream operations. Some of the key projects include Eni’s Ravenna cluster, ExxonMobil’s Gulf Coast CO₂ transport and storage network and Northern Lights, which is jointly owned by Equinor, Shell and TotalEnergies, for advancing offshore CO₂ transport and storage in Norway.
“As of June 2026, the operational carbon capture base remained modest, with more than 140 projects globally across multiple industries and a cumulative capacity of 62 million tonnes per annum (mtpa),” noted Ravindra Puranik, Oil and Gas Analyst at GlobalData. “The energy sector accounted for the bulk of this capacity. However, most future capture capacity remains concentrated in the feasibility and FEED stages of project development.”
The current phase of the CCUS market reflects that the sector has moved beyond pilot-scale interest, but many projects have yet to clear the commercial, regulatory, and infrastructure hurdles required for construction and commissioning. The availability of shared CO₂ pipelines, shipping routes and storage hubs will be critical in de-risking these projects and improving the economics of capture investments.
Despite the strong project pipeline for CCUS, the decade is likely to be defined by selective delivery rather than uniform expansion, the report indicated. Many announced projects remain exposed to financing risk, cost inflation, regulatory uncertainty, and delays in securing long-term CO₂ offtake or storage contracts. Without sufficient transport infrastructure and storage capacity, captured CO₂ cannot be permanently sequestered at scale, which can slow or limit capture project development. Companies are unlikely to advance capture facilities without a reliable route to store the CO₂.
Puranik concluded, “The US 45Q tax credit, the European Union’s ETS and Canada’s carbon pricing mechanism support project economics. However, high capital and operating costs, inadequate CO₂ transport and storage infrastructure, permitting delays, long-term liability and public skepticism remain critical for the mass CCUS deployment.”
CONNECT WITH THE TEAM