
Read this article in 中文 Français Deutsch Italiano Português Español
Natural gas and LNG markets poised for rapid normalization, Macquarie says
June 23, 2026
Macquarie identified LNG as one of the commodities facing lower price expectations compared with earlier forecasts
Global natural gas and LNG markets could return to more stable conditions sooner than many market participants expect following the reopening of the Strait of Hormuz, according to a new commodities outlook from Macquarie.
The firm said energy markets demonstrated remarkable resilience during the disruption of Middle East energy flows, with supply chain flexibility, excess inventories and alternative trade routes helping limit the impact on global energy supplies. As shipping routes normalize, Macquarie expects downward pressure on LNG prices and a return to a more balanced market environment during the second half of 2026.
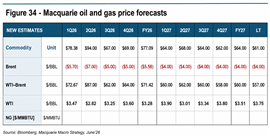
In its latest Commodities Compendium, Macquarie identified LNG as one of the commodities facing lower price expectations compared with earlier forecasts, citing the combination of temporary supply disruptions, a rapid market recovery and growing liquefaction capacity. The firm reduced its 2026 outlook for Japan-Korea Marker (JKM) LNG prices by 8% compared with previous forecasts.
The revised outlook reflects expectations that global LNG trade will adapt quickly as shipping routes through Hormuz reopen and new supply projects continue to enter service.
“Markets tend to solve problems more efficiently than expected,” the report said, noting that the energy sector has benefited from substantial reserves, flexible supply chains and the ability to reroute cargoes during periods of disruption.
Macquarie forecasts JKM LNG prices averaging $16.48/MMBtu in 2026 before falling to $12.81/MMBtu in 2027 and declining further over the following years as additional supply enters the market. The firm expects LNG prices to moderate despite continued demand growth from Asia and increasing global energy consumption.
The outlook comes as global economic growth remains resilient despite geopolitical tensions. Macquarie expects global GDP growth to accelerate toward 3% by late 2027, supported by expanding technology investment and recovering industrial activity. Stronger economic growth could provide support for natural gas demand even as commodity prices ease.
For the natural gas industry, the report suggests that market fundamentals remain supportive of continued investment in LNG export infrastructure, pipelines and compression assets, even as commodity prices retreat from recent highs. Lower LNG prices are expected to result primarily from increasing supply availability rather than weakening demand.
Macquarie also noted that the disruptions of 2026 may ultimately leave global energy supply chains more diversified and flexible than before. New trade routes and operational adjustments developed during the crisis are expected to remain in place, improving the industry’s ability to respond to future disruptions.
While the firm sees risks if geopolitical tensions flare again in the Middle East, its base case assumes unrestricted shipping through Hormuz and a continued normalization of global energy flows. Under that scenario, LNG markets are expected to transition from a disruption-driven environment toward one increasingly shaped by new export capacity and long-term supply growth.
CONNECT WITH THE TEAM