
Read this article in 中文 Français Deutsch Italiano Português Español
Qatar LNG disruption could reshape global supply outlook: Wood Mackenzie
March 19, 2026
Damage to Ras Laffan facilities removes nearly 20% of global LNG supply, raising risk of prolonged market tightening
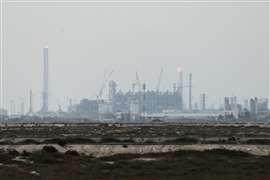 QatarEnergy’s liquefied natural gas (LNG) production facilities, amid the U.S.-Israeli conflict with Iran, in Ras Laffan Industrial City, Qatar. REUTERS/Stringer/File Photo
Iran’s missile attacks on Qatar’s Ras Laffan Industrial City have caused extensive damage to key gas infrastructure, halting production and fundamentally altering the outlook for global LNG markets, according to analysis released by Wood Mackenzie.
The March 18 strike damaged the Pearl gas-to-liquids (GTL) facility, with subsequent attacks impacting several LNG facilities. Wood Mackenzie said further assessment is required to determine the full extent of the damage.
Qatari LNG production has been halted since March 2, with force majeure declared on March 4. The disruption has removed approximately 80 million tonnes per annum (Mtpa) of supply from the market, representing about 19% of global LNG capacity.
“Market expectations had been for a short disruption, with a controlled restart restoring supply to pre-conflict levels by mid-2026. That outlook now appears increasingly unlikely,” said Kristy Kramer, head of LNG strategy and market development at Wood Mackenzie. “A more prolonged outage would further tighten global supply and keep prices elevated for longer.”
Restart timelines extend
Prior to the attacks, Wood Mackenzie had expected Qatari LNG production to return to full capacity within four to six weeks, based on a phased restart of upstream operations and liquefaction trains. The firm now expects that timeline to extend, depending on the scale of damage and required repairs.
The disruption also raises uncertainty around Qatar’s North Field East expansion project, which is designed to add 32 Mtpa of new capacity. Originally targeted for startup in late 2026 and already delayed into 2027, the project now faces the potential for further setbacks.
Wood Mackenzie said additional delays could constrain global LNG supply growth through 2027 and 2028, limiting the market’s ability to rebalance.
Supply growth at risk
Before the attacks, the firm had forecast global LNG supply growth of 35 Mt in 2026. With Qatar producing an average of 6.7 Mt per month in 2025, Wood Mackenzie said a disruption lasting five to six months would push annual global supply into year-on-year decline.
“Even if supply were maintained at 2025 levels, the market would still face demand destruction in Asia, lower storage injections in Europe, and sustained upward pressure on gas and LNG prices,” said Daniel Toleman, research director for global LNG at Wood Mackenzie. “Each additional month of disruption removes around 1.5% from annual global LNG availability.”
Regional impacts
Asian markets are expected to be most affected, with the region accounting for about 90% of Qatari LNG cargoes in 2025. Wood Mackenzie identified Bangladesh, India and Taiwan as particularly exposed due to limited alternatives and sensitivity to rising energy costs.
The firm said Asian LNG demand, previously forecast to grow by 10 Mt, had already been reduced to 2 Mt under a two-month disruption scenario. A longer outage is expected to push demand into decline.
In Europe, reduced LNG availability is expected to limit storage injections and increase reliance on alternative fuels. Wood Mackenzie said storage levels could reach about 70%, compared with 76% in October 2021 during disruptions to Russian pipeline supply.
With supply tightening, LNG operators are expected to prioritize output across existing facilities. Wood Mackenzie said planned maintenance, estimated at 5 Mt in the second quarter of 2026, is likely to be deferred where possible.
“Geopolitics continue shaping gas and LNG markets, and despite the industry’s large scale, it lacks flexibility to absorb major disruptions, creating market volatility,” Kramer said. “We expect buyers to prioritize LNG supply security with a renewed focus on diversity.”
Wood Mackenzie said the disruption is likely to increase the value of supply diversification, contract flexibility and portfolio approaches, as market participants seek to manage exposure to geopolitical risk.

CONNECT WITH THE TEAM